What Home Insurance Usually Covers on a Roof
Home insurance usually covers sudden, accidental roof damage, such as shingles torn off by wind, hail impacts or a tree falling on the house. It usually does not cover wear and tear, age-related failure, poor maintenance or faulty installation.
| Usually covered |
Usually not covered or limited |
| Wind lifting or tearing off shingles |
Shingles worn out from age and UV |
| Hail bruising or fracturing shingles |
Granule loss from normal weathering |
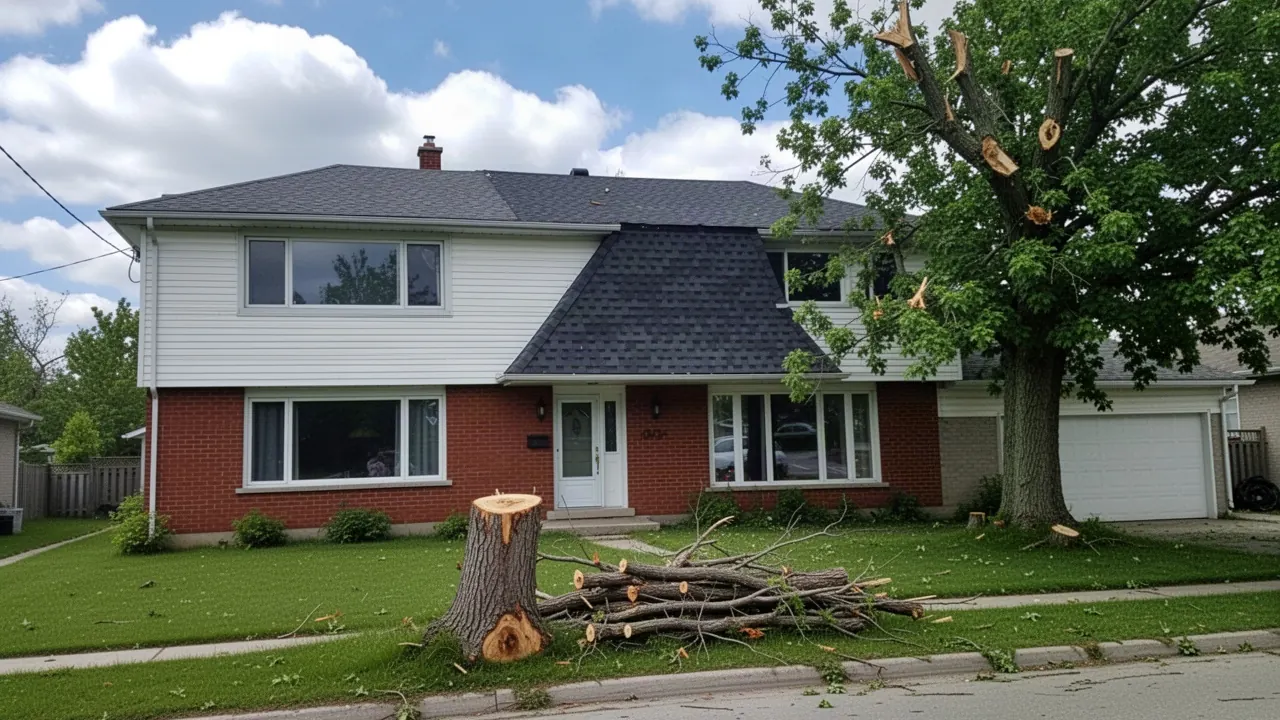
| Trees and limbs falling on the roof |
Leaks from long-term flashing deterioration |
| Sudden interior water damage after a storm |
Gradual leaks, rot and mould over months |
| Fire and lightning damage |
Damage from poor installation or no maintenance |
Wording varies between policies, so your declarations page and wording decide what applies. Interior water damage from an ice dam is often covered, while the ice dam itself and repeat events may not be.
Will insurance cover a 20-year-old roof in Ontario? Often yes, but not always at full value. Many policies pay actual cash value on an older roof, meaning replacement cost minus depreciation for age, and some insurers limit or exclude coverage once a roof passes a certain age.
Before you call your insurer, gather what an adjuster will ask for:
- The date and time of the storm, plus any Environment Canada warning issued for it.
- Ground-level photos of the roof, debris on the lawn and any fallen trees or limbs. Stay off the roof.
- Interior photos of stains, drips and wet insulation, taken before anything is cleaned up.
- Receipts for tarping, water extraction or other emergency work.
- Your roof's age, from a past invoice, home inspection report or warranty registration.
Ottawa has seen how fast storms can strip a roof. The September 2018 tornado tore roofs off homes in Arlington Woods and Craig Henry in Nepean, and the May 2022 derecho brought gusts near 190 km/h across the region.